Achieving long-term financial autonomy requires putting capital to work through productive assets. Understanding investing basics allows you to move beyond cash savings—which steadily lose purchasing power to inflation—and transition into systematic ownership of revenue-generating businesses, debt securities, and real assets.
Investing is often mistaken for speculative trading or market timing. In reality, sound wealth creation relies on asset allocation, fee minimization, time horizon expansion, and consistent capital contribution. Mastering these core principles shields your net worth from macroeconomic volatility while harnessing the mathematical power of compounding returns.
Key Takeaways
- Time Horizon Dictates Risk Tolerance: Capital needed within 3 to 5 years belongs in cash equivalents or short-duration fixed income, whereas long-term reserves can absorb equity market volatility to maximize returns.
- Compound Growth Demands Consistency: Consistent, automated contributions over multi-decade periods amplify returns exponentially through dividend reinvestment and capital appreciation.
- Diversification Minimizes Idiosyncratic Risk: Broad-market exchange-traded funds (ETFs) and low-cost index funds eliminate the risk of individual corporate failures without sacrificing aggregate market yield.
- Expense Ratios Erode Final Wealth: High management fees and front-end loads compound negatively over time, significantly reducing the net terminal value of an investment portfolio.
Foundational Asset Classes: Comparative Allocation Matrix
A balanced portfolio spreads risk across distinct asset categories with varying risk-return profiles.
| Asset Class | Primary Risk Profile | Expected Return Mechanism | Typical Time Horizon | Best Used For |
| Equities (Stocks / Index Funds) | Moderate to High volatility; capital fluctuation | Capital appreciation, corporate dividends | 5–10+ years | Core long-term growth and inflation hedging |
| Fixed Income (Bonds / Notes) | Low to Moderate; interest rate sensitivity | Regular coupon payments, principal return | 2–7 years | Portfolio stabilization, capital preservation, predictable cash flow |
| Cash & Equivalents (HYSA, T-Bills) | Negligible nominal risk; purchasing power risk | Accrued risk-free interest yield | < 1–2 years | Emergency reserves and short-term capital liquidity |
| Real Estate / Real Assets (REITs) | Moderate; illiquidity and debt leverage | Rental dividends, property appreciation | 5–10+ years | Inflation-linked income and tangible diversification |
3 Core Principles of Practical Investing Basics
Building a durable portfolio requires executing proven financial principles with discipline rather than reacting to short-term headlines.
1. The Mechanics of Compounding and Dollar-Cost Averaging
Wealth accumulation relies on exponential math rather than aggressive speculative timing.
- Dollar-Cost Averaging ($DCA$): Automating fixed-dollar investments at regular intervals (e.g., bi-weekly or monthly) removes emotional decision-making. You naturally purchase more shares when prices drop and fewer shares when valuations rise, averaging your cost basis downward over time.
- The Compounding Velocity: Reinvesting corporate dividends and interest payments accelerates share accumulation. Over a 20- to 30-year horizon, the compound return on reinvested gains typically overtakes initial principal deposits.
2. Broad Diversification via Low-Cost Index Funds
Attempting to hand-pick winning equities regularly underperforms broader index benchmarks over decades.
- Market-Cap Indexing: Broad-market funds (such as total stock market or S&P 500 index funds) offer immediate ownership across hundreds of corporations across diverse market sectors.
- Expense Ratio Efficiency: Opt for passively managed funds with expense ratios below 0.10% annually. Paying 1% or more in active mutual fund fees can consume more than 20% to 30% of your potential lifetime portfolio returns.
Account Architecture: Tax-Advantaged vs. Taxable Vehicles
Structuring where you hold investments is just as crucial as what you purchase:
- Employer-Sponsored Accounts (e.g., 401k, 403b): Always capture any available employer matching contribution first—this represents an immediate 100% risk-free return on capital.
- Individual Retirement Accounts (Traditional vs. Roth IRAs): Utilize Roth structures if you expect your future marginal tax bracket to exceed your current rate, allowing investments to compound and withdraw 100% tax-free in retirement.
- Taxable Brokerage Accounts: Deploy surplus capital beyond retirement account caps into taxable accounts, prioritizing tax-efficient broad-market index ETFs that trigger minimal capital gains distributions until sold.
Launching Your Long-Term Investment Strategy
Successful wealth accumulation is a marathon of consistency rather than a sprint of speculation. By mastering investing basics—automating contributions, diversifying through broad-market indexes, and protecting your capital with a dedicated emergency buffer—you remove emotion from financial decisions. A disciplined, systematic approach to investing turns your current income into enduring financial freedom and long-term security.
Frequently Asked Questions About Investing Basics
How much money do you need to start investing?
Thanks to modern fractional share trading and zero-commission brokerage accounts, you can begin investing with as little as $1 to $5. Many top-tier index funds and ETFs no longer have mandatory minimum purchase requirements, making diversified global markets immediately accessible to beginners.
What is the difference between an ETF and an index mutual fund?
Both exchange-traded funds (ETFs) and index mutual funds can track the same underlying market index and offer broad diversification at low costs. The primary operational difference is that ETFs trade throughout the day like individual stocks at real-time market prices, whereas mutual fund transactions settle once per day after the market closes at the net asset value ($NAV$).
How do you determine your asset allocation?
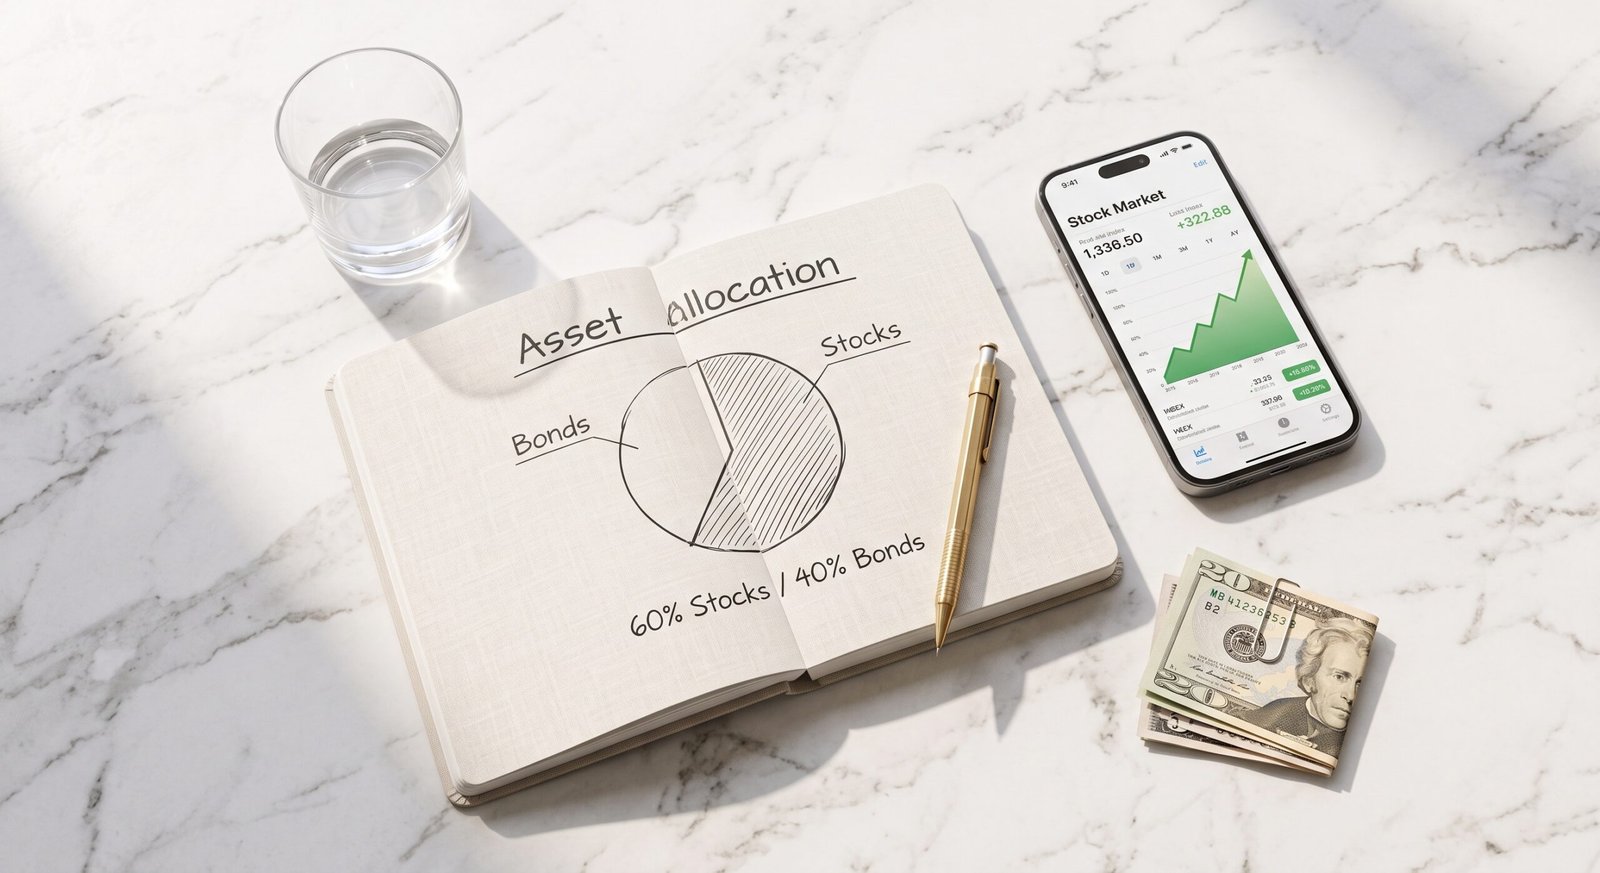
Asset allocation depends largely on your time horizon and emotional capacity to withstand drawdowns. A classic baseline rule subtracts your age from 110 or 120 to find the equity percentage of your portfolio, placing the remainder in fixed income or cash equivalents. Younger investors with multi-decade horizons can tolerate aggressive, equity-heavy allocations (such as 80% to 90% equities), while those near retirement typically shift toward bonds to preserve capital.
1 thought on “Investing Basics: Strategic Guide to Portfolio Growth”